George Mudie
Reducing App Store Dependence: Building a Direct Subscription Model
 George Mudie · · 4 min read
Key takeaways
Tap to advance- Despite being UK's highest-grossing non-game app, strategic success meant reducing Apple App Store dependence for better margins
- Platform fees of 30% and limits on direct customer contact affect the economics of premium content businesses at scale
- Dual-channel strategy uses app stores for market validation while building direct subscriptions as primary revenue engine
- Platform strategies should serve business objectives, not define them - build customer relationships independent of distribution mechanisms
The Times & Sunday Times iPad app holds an unusual distinction: it’s the highest-grossing non-game app in the UK App Store. Yet our most important strategic decision was deliberately reducing our dependence on app store revenue-sharing models.
Platform Dependency vs. Revenue Control
While Apple’s App Store generated $10 billion in revenue during 2014 across 1.4 million apps, the mathematics reveal a concerning concentration risk. That’s an average of $7,100 per app annually, a figure that shows how thinly revenue is spread across the platform.
Our strategic analysis revealed three platform considerations:
Customer relationship constraints. The in-app purchase model limits direct customer communication to push notifications. For premium content businesses, customer relationships are a primary competitive asset, so retaining direct contact matters for long-term positioning.
Revenue sharing economics. The 30% platform fee affects margins, and the effect grows with scale. For content businesses with existing production costs, platform fees can significantly reduce profitability.
Market expansion limitations. App Store bundling functionality only applies to paid apps, which represent 4% of total applications. This limits the range of revenue models that can be tested.
Strategic Platform Arbitrage
Rather than optimising within platform constraints, we developed a dual-channel strategy that maximised the benefits of each approach:
App Stores as market validation tools. We leveraged Apple’s global distribution to test market demand across non-domestic territories including the US, Australia, Canada, Switzerland, and France. This provided invaluable market intelligence for international expansion decisions without requiring significant upfront investment.
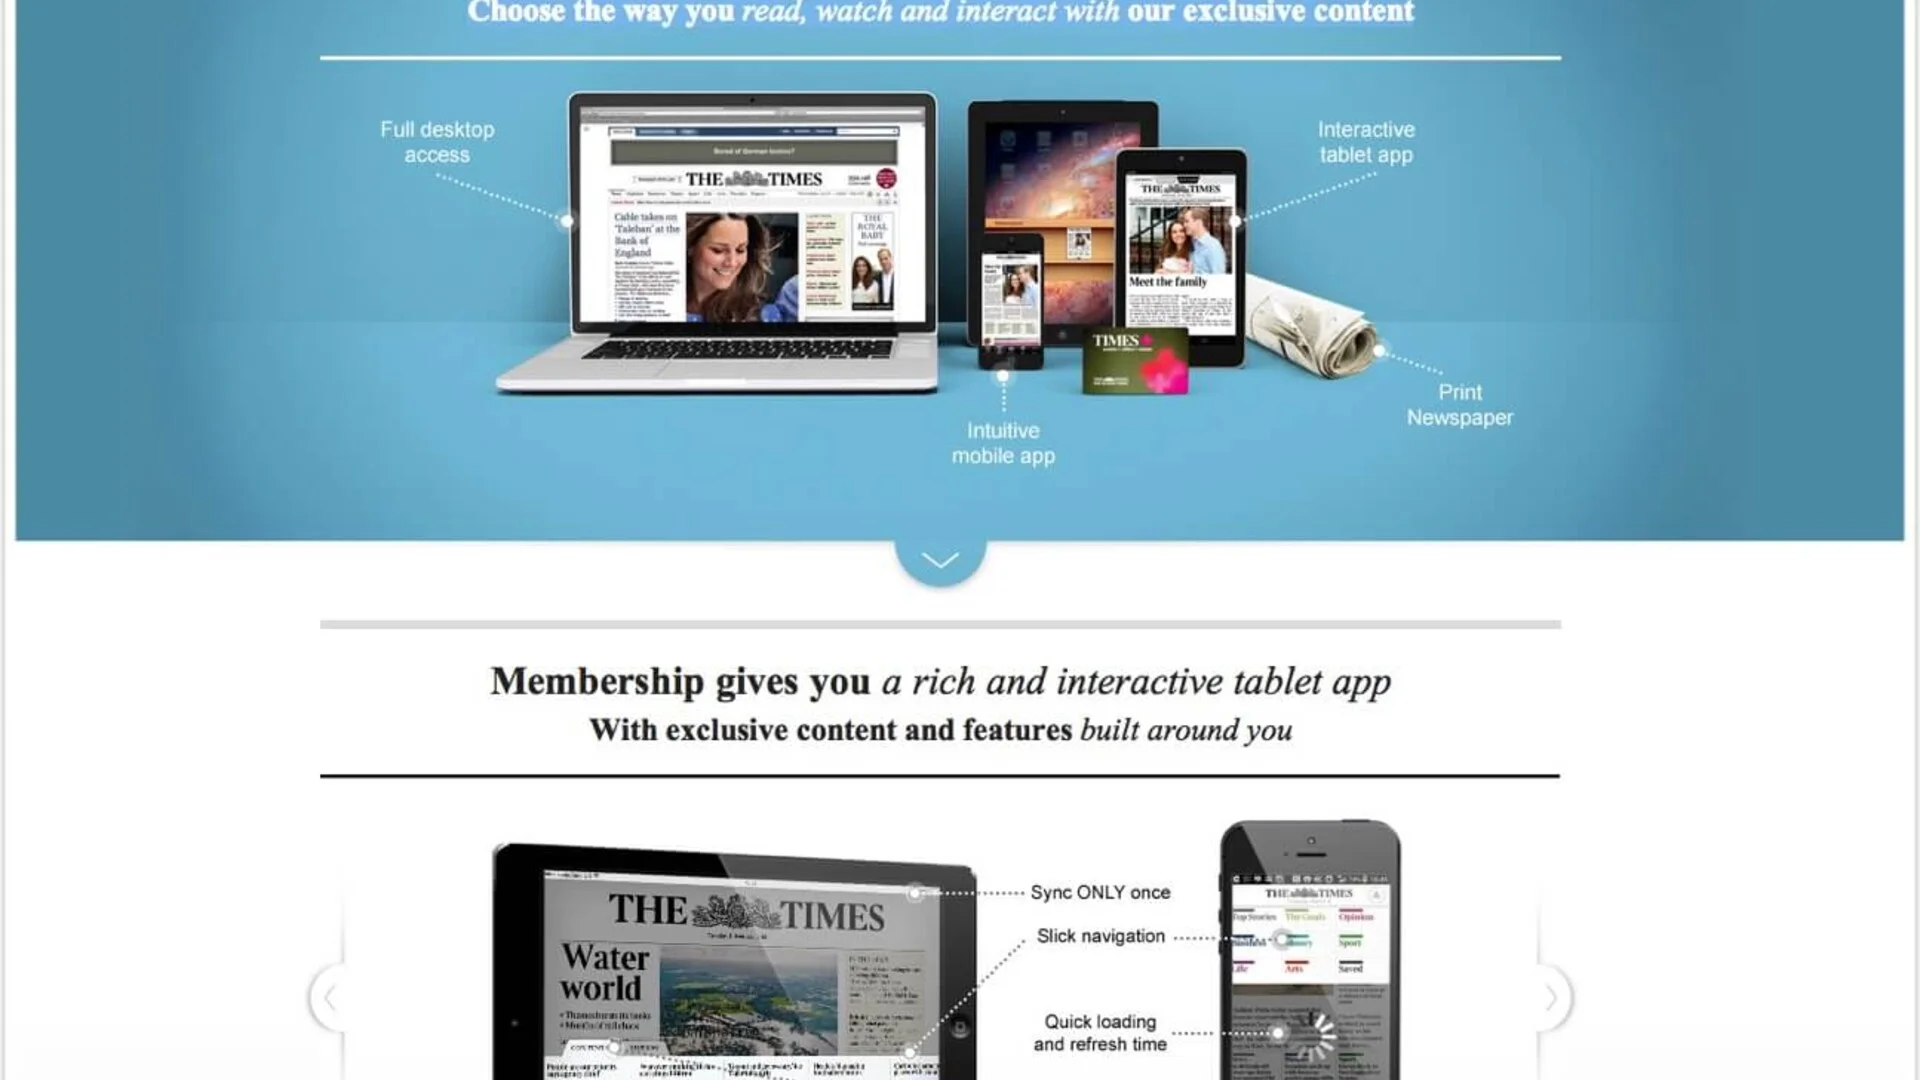
Direct subscriptions as primary revenue engine. Our direct subscription model offers customers integrated access across smartphone apps, tablet applications, web platforms, and exclusive membership benefits. This creates genuine value bundling rather than artificial platform restrictions.
Revenue Model Performance Comparison
The results validate our platform strategy approach. Despite falling from 5th to 8th position in Apple’s annual rankings, this reflects strategic success rather than market failure.
Position decline occurred due to:
- Freemium games improving in-app purchase optimisation
- Our deliberate revenue shift toward higher-margin direct subscriptions
Financial performance improved because direct subscription margins significantly exceed App Store revenue sharing arrangements.
Platform Economics for Executive Decision-Making
Our experience demonstrates three critical principles for platform strategy:
Platform leverage, not platform dependence. Use platform distribution capabilities for customer acquisition and market validation, but retain direct customer relationships for revenue optimisation.
Margin architecture drives sustainable growth. Platform fees that seem reasonable at startup scale become a larger share of costs at enterprise scale. Plan revenue model transitions before platform dependency becomes financially constraining.
Customer value proposition differentiation. Direct subscription models allow value bundling that platform models do not support. This creates competitive advantages that platform-dependent competitors cannot replicate.
The Android Landscape
Market data from Google Play reinforces our strategic approach. Market data points to lower average willingness to pay for premium content among Android users, which makes monetisation more challenging on that platform.
The mobile platform landscape rewards different strategic approaches:
- Indies should maximise platform leverage through freemium IAP models
- Established content companies should use platforms for distribution while building direct customer relationships
- Enterprise applications require platform-independent revenue models from inception
Strategic Framework: Beyond Platform Optimisation
Monument Valley’s financial disclosure provides useful benchmarks for independent developers, but also highlights why platform strategies must differ based on organisational scale and objectives.
For content companies, the strategic imperative isn’t platform optimisation - it’s platform transcendence. Success requires building customer relationships that exist independently of any single distribution mechanism.
Our App Store Optimisation work continues, but as one component of a diversified customer acquisition strategy rather than the primary revenue foundation. This approach provides sustainable competitive positioning while maintaining platform relationship benefits.
The fundamental insight: Platform strategies should serve business objectives, not define them. When platforms become constraints rather than enablers, successful companies build alternative pathways to customer value creation.
Image courtesy of TNL